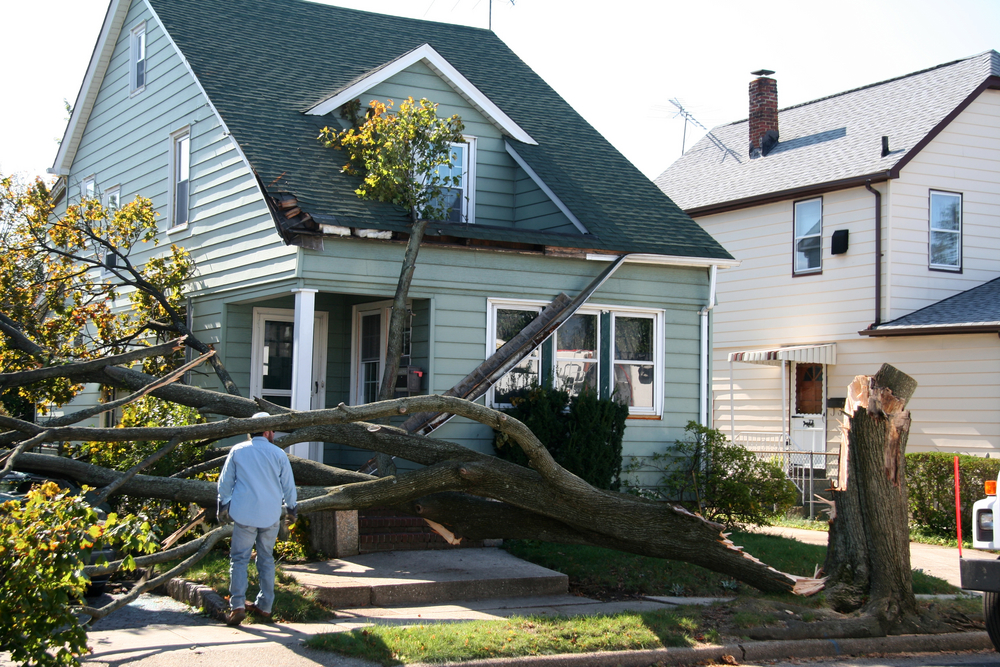
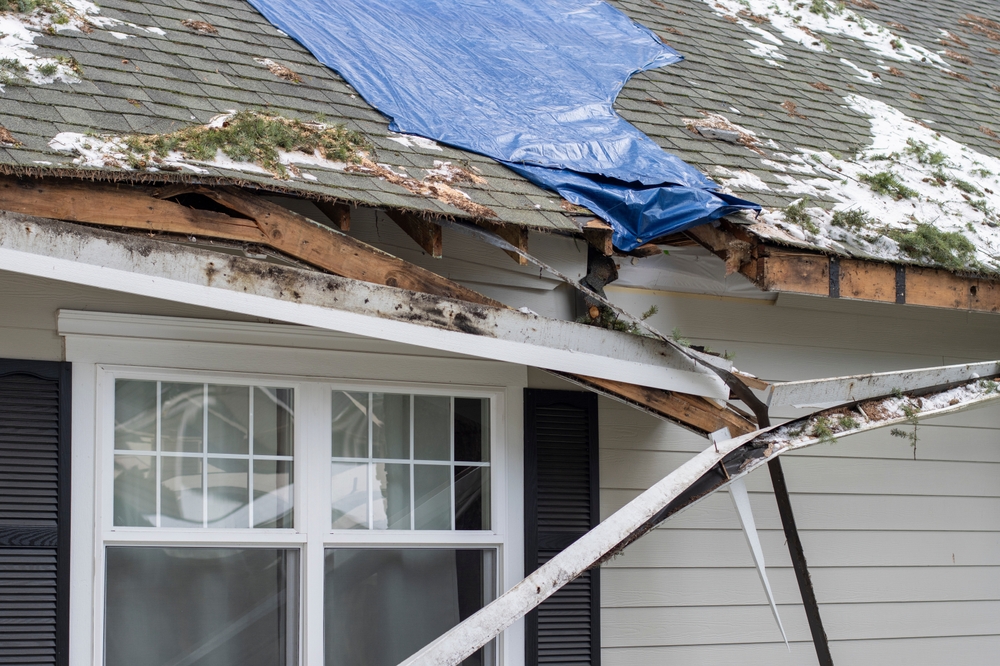
Damage to your home from a fire, storm, or other unexpected event can be stressful. Having homeowners insurance can help protect you financially from covered losses, but filing a claim doesn’t guarantee it will be approved.
Home insurance claims can be denied for several reasons, including policy exclusions, insufficient documentation, missed policy requirements, or damage that simply isn’t covered. Understanding your policy before something happens can help you avoid surprises during the claims process.
Below are six common reasons homeowners insurance claims may be denied in Georgia and what you can do to reduce your risk of running into problems.
Common Reasons for Homeowners Insurance Claim Denials in Georgia
-
Waiting Too Long to File
One of the most important steps when filing a homeowners insurance claim is notifying your insurer promptly.
Home insurance policies typically include requirements for reporting a loss within a certain timeframe or providing prompt notice. Waiting can also make a claim harder to evaluate. Damage may worsen, evidence may disappear, or it may become harder to determine the original cause.
For example, an unreported water leak can lead to additional damage over time, while storm damage may become harder to document if repairs are made before the insurer has an opportunity to inspect it.
Review your policy for its specific notification requirements and contact your insurer as soon as reasonably possible after discovering damage.
-
Liability Claim Falls Outside Your Coverage
Not every homeowners claim involves damage to the house itself. Your policy may also include personal liability coverage that can help if you’re legally responsible for certain injuries or property damage involving someone else.
Examples could include a guest getting hurt on your property or damage to someone else’s property. Whether a particular incident is covered depends on the circumstances, policy limits, exclusions, and other terms.
Liability claims may be denied when the incident falls outside the policy’s coverage or is subject to an exclusion. That’s why understanding your family liability protection on homeowners insurance in Georgia can help you know what protection you have before a claim occurs.
-
Coverage Exclusions
One of the simplest reasons an insurance claim can be denied is that the cause of the damage isn’t covered by the policy.
An exclusion is a type of loss, event, or circumstance that your insurance policy specifically says it doesn’t cover. Standard homeowners policies don’t protect against every possible problem that could damage your home.
For example, homeowners insurance generally doesn’t cover flooding caused by rising surface water, so separate flood insurance may be needed for that risk. Other losses may also be excluded or limited depending on your policy, endorsements, and circumstances.
Maintenance-related problems and normal wear and tear are also generally treated differently from sudden covered losses. If a roof has been deteriorating for years, for example, homeowners insurance generally isn’t a substitute for routine home maintenance.
Reviewing common home insurance limitations in Georgia can help you identify possible gaps in your protection. You can then talk with your insurance provider about endorsements, separate policies, or other coverage that may be available.
-
Damages Doesn’t Exceed Your Deductible
Your deductible is the amount you’re responsible for paying toward a covered property claim before your insurer pays its portion.
Suppose a covered repair costs $800, but the applicable deductible is $1,000. There generally wouldn’t be an insurance payment because the covered loss doesn’t exceed the deductible.
The deductible that applies can also depend on the policy and type of loss. Rather than assuming every claim has the same deductible, review your policy so you know what you would be responsible for paying.
Understanding Georgia home insurance deductibles before damage happens can help you make more informed decisions when choosing coverage and filing a claim.
For smaller losses, consider getting a repair estimate and comparing it with the applicable deductible, while still following your policy’s notice requirements.
-
Incorrect or False Information
Accuracy matters when you’re filing a homeowners insurance claim.
A mistake doesn’t automatically mean fraud, but incorrect, incomplete, or inconsistent information can slow down an investigation or create questions about the claim. Intentionally providing false information can have much more serious consequences.
When filing a claim, provide accurate information about what happened and the damage you discovered. Keep supporting documentation such as:
- Photos and videos of the damage
- Records of damaged belongings
- Relevant communication with your insurer
Good documentation can help your insurer evaluate the loss and determine what your policy covers.
Avoiding other common home insurance mistakes in Georgia can also help you better understand and maintain your coverage.
-
Possible Claim-Handling Error
Sometimes you may believe your claim was denied incorrectly.
If that happens, don’t assume the denial is the end of the process. Start by requesting or carefully reviewing the insurer’s written explanation for the decision. Compare the reasons given with the terms, exclusions, and coverage described in your policy.
If something doesn’t add up, contact the insurer or claims adjuster and ask questions. You may be able to provide additional documentation or request another review.
If you’re still unable to resolve the issue, you can contact the Georgia Office of the Commissioner of Insurance and Safety Fire for information about filing a consumer complaint or getting assistance with an insurance-related concern.
What to Do If Your Home Insurance Claim Is Denied
A denied claim can be frustrating, but there are steps you can take to better understand the decision and determine what to do next.
Start with the denial letter. It should explain why the insurer denied the claim or why certain damage wasn’t covered. Then compare that explanation with your policy.
Next:
- Review your policy. Look at the applicable coverage, exclusions, limits, deductibles, and claim requirements.
- Gather supporting evidence. Collect photos, videos, receipts, estimates, invoices, and other documentation related to the loss.
- Contact your insurer. Ask your adjuster to explain anything in the denial that isn’t clear.
- Request another review if appropriate. Find out whether your insurer has a process for reconsidering or disputing a claim decision.
- Keep records. Save copies of correspondence, claim documents, estimates, and notes from conversations.
- Seek additional help if necessary. If you still believe the claim wasn’t handled correctly, consider contacting the Georgia Office of Commissioner of Insurance and Safety Fire or seeking qualified professional guidance.
Don’t ignore deadlines listed in your policy or claim correspondence while you’re disputing a decision.
How to Avoid Common Home Insurance Claim Problems
Preparation can’t guarantee that a claim will be approved, but it can make the claims process easier.
After discovering damage, document it with photos or videos before making permanent repairs when possible. Take reasonable steps to prevent additional damage when it’s safe to do so and keep receipts for temporary repairs or related expenses.
A few other good habits include:
- Maintain an up-to-date home inventory.
- Understand what your policy covers and excludes.
- Know your deductible and coverage limits.
- Keep receipts and records for major home improvements and valuable belongings.
- Perform routine home maintenance.
- Review your policy periodically and after major changes to your home.
It’s also helpful to learn about common home insurance claims before you ever need to file one. Knowing what commonly goes wrong can help you understand your coverage and prepare ahead of time.